TL;DR
ATMs took over routine cash services, but US teller employment rose modestly from about 500,000 in 1980 to 550,000 in 2010 as banks expanded their branch networks. Mobile banking later changed the pattern: teller employment fell to 339,200 in 2025, while Germany’s branch count also declined sharply.
Barclays introduced its first cash machine outside a branch in Enfield, north London, on June 27, 1967. Actor Reg Varney demonstrated it by withdrawing up to £10 in one-pound notes. The branch closed at 3:30 p.m.; the machine could dispense cash after closing. According to the source account, the machine used a special paper cheque marked with carbon 14 and a personal code, rather than a plastic card.

Get everyday essentials delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
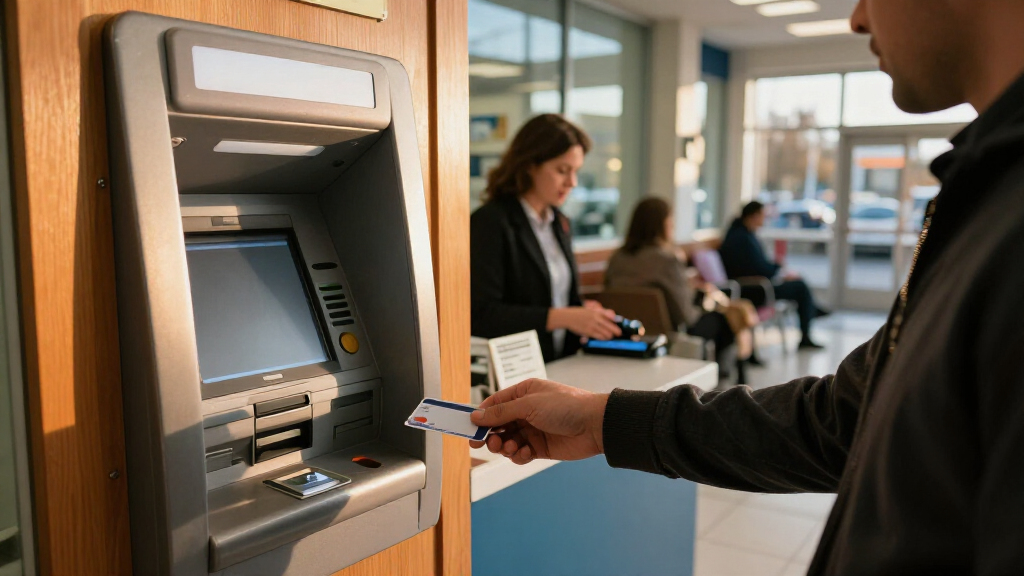
The machines were designed to handle core teller duties, especially dispensing cash and taking deposits. Yet US teller employment did not fall as ATMs spread. The account, citing economist James Bessen’s analysis as summarized by MIT economist David Autor, says the number of tellers rose from about 500,000 in 1980 to 550,000 in 2010. Over a separate period, from 1995 to 2010, the US ATM count roughly quadrupled, from about 100,000 to 400,000.
Bessen’s explanation, as presented in the account, is that ATMs reduced staffing needs at individual branches while making branches cheaper to operate. In a typical US urban market, teller staffing per branch fell from about 20 to 13 between 1988 and 2004, while the number of bank branches in US cities grew 43%. The account says deregulation that allowed banks to open branches more freely also contributed to expansion.
ATMs and bank tellers The paradox
ATMs reduced routine work at each branch, yet US teller employment initially rose as banks expanded their networks. Later, teller jobs and branch counts fell.
How ATMs changed branch work
Machines took on routine cash services, while lower branch costs helped banks expand.
- Teller staffing fell from about 20 to 13 between 1988 and 2004.
- ATMs handled cash withdrawals and deposits.
- Branch numbers grew 43% from 1988 to 2004.
- Total teller employment rose from about 500,000 in 1980 to 550,000 in 2010.
Banking shifted toward mobile
In 2023, mobile banking was the main method for more US households than teller service.
Branches contracted
The later decline appeared in both US teller jobs and Germany’s branch network.
BLS figures cited in the account fell from about 600,500 jobs in 2008 to 339,200 in 2025.
The reported count fell from 45,467 at the end of 2004 to 16,799 at the end of 2025.
How Branch Growth Offset Automation
The history complicates simple predictions that automating a job’s core task will make the occupation disappear. In the period described, ATMs reduced the number of tellers needed at each branch, but lower branch operating costs and network expansion helped support total teller employment. That distinction matters when evaluating the effects of automation: changes in staffing at each location do not, by themselves, establish what happens to total employment.
The account also describes a later shift associated with mobile banking. In 2023, 48.3% of US households with a bank account said mobile banking was their main method, compared with 15.1% who mainly used a teller. Separately, Bureau of Labor Statistics figures cited in the account put US teller jobs at about 600,500 in 2008 and 339,200 in 2025. The figures show a later decline, though they do not by themselves prove mobile banking was its sole cause.
For customers, the changes affect how and where routine banking is available. Fewer tellers and branches may mean more reliance on digital services or cash machines, while people who need in-person help may have fewer nearby options. The source gives employment and branch counts, but does not quantify effects on customer access.
Popular right now

Breville Barista Express Espresso Machine with Built-In Grinder, Brushed Stainless Steel

KitchenAid Artisan Series 5-Quart Tilt-Head Stand Mixer, Juniper (KSM150PS)

KitchenAid 5.5-Quart Bowl-Lift Stand Mixer, Porcelain White
As an affiliate, we earn on qualifying purchases.
From Enfield to Mobile Banking
The first Barclays machine arrived in 1967, when cash withdrawals generally required a visit during bank hours. A German cash machine opened in Tübingen on May 27, 1968, with a maximum withdrawal of 400 marks, according to the account. In September 1969, Chemical Bank installed a Docutel cash dispenser in Rockville Centre, New York; the account cites the Smithsonian and Computer History Museum for that date.
The US branch figures give further context to the employment pattern. FDIC counts cited in the source show commercial bank offices, including head offices and branches, rising from 58,937 at the end of 1988 to 77,302 at the end of 2004. The count peaked at 88,522 in 2012, then stood at 72,658 in 2025. These totals cover offices nationwide and are distinct from the account’s 43% increase in branches in US cities from 1988 to 2004.
The later trend differs from the ATM-era expansion. In Germany, the account reports bank branches fell from 45,467 at the end of 2004 to 16,799 at the end of 2025. It also says cash machines are retreating in Germany, China and Japan, but gives no counts or dates for those machine closures.
What the Counts Cannot Show
The figures summarized in the account describe employment and branch trends, but do not establish how much of the later teller-job decline was caused by mobile banking, branch consolidation, or other changes. The source also does not provide a comparable teller-employment series for Germany, China or Japan, despite noting declines in branches or cash machines there. The reasons for cash-machine retreats and their scale remain unspecified.
The account reports that teller work shifted toward advice and sales as routine cash handling moved to machines. It does not quantify how many workers moved into those duties, changed roles, or left banking. Its figures also cover different periods and measures: teller employment, full-time-equivalent estimates, branch counts and ATM counts should not be treated as directly interchangeable.
The Next Phase of Branch Change
The source account provides figures through 2025 but names no forthcoming report, policy change or industry milestone. The next useful evidence would be updated teller-employment, branch and cash-machine counts, alongside data showing how customers use in-person, ATM and mobile services. Those measures could help clarify whether the later pattern continues and how it affects access to banking.
Key Questions
Did ATMs eliminate bank teller jobs?
No. The account says US teller employment rose modestly, from about 500,000 in 1980 to 550,000 in 2010, even as ATMs spread. Staffing per branch fell, while branch numbers grew.
Why did teller employment rise as ATMs spread?
James Bessen’s explanation, as summarized in the account, is that ATMs lowered branch operating costs. Banks could use fewer tellers at each location while opening more branches, supporting total employment.
When did US teller employment begin to fall in the figures cited?
The account cites Bureau of Labor Statistics counts of about 600,500 teller jobs in 2008 and 339,200 in 2025. It does not identify one cause for the decline.
What happened to bank branches in Germany?
The account reports that Germany’s branch count fell from 45,467 at the end of 2004 to 16,799 at the end of 2025.
Source: Thorsten Meyer AI